Licensed and Insured Independent Pros
Every contractor we connect you with runs an independent local business that carries its own license and insurance. Ask for the certificate of insurance at the first visit; a good contractor has it ready.
Once the drying gear is hauled out, most homes are left with open walls, bare subfloor and missing trim. Rebuilding all of that is restoration, which is its own trade with its own crews.
Our referral line links Lapel homeowners with independent, licensed and insured contractors who handle the rebuild from drywall to paint. You get a written, line-itemed scope before anyone picks up a hammer.
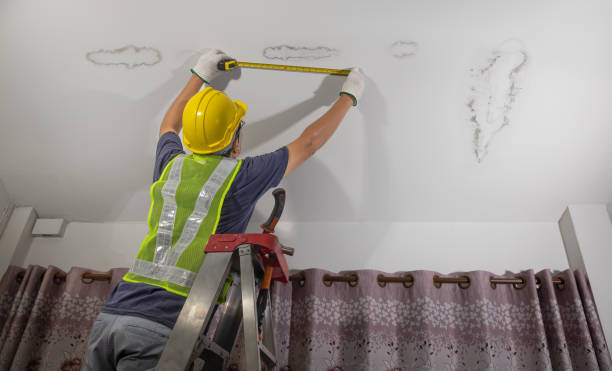
A rebuild after water damage is finish carpentry with an insurance file attached. The independent pros in our network do that kind of work every week in Lapel.
Every contractor we connect you with runs an independent local business that carries its own license and insurance. Ask for the certificate of insurance at the first visit; a good contractor has it ready.
The estimate comes in writing, broken out by square feet of drywall, linear feet of baseboard and hours of labor. Many write it in the line-item style adjusters already use, which cuts the back and forth on the claim.
Restoration is not usually a midnight job, yet a slow bid can hold up your entire claim. The dispatcher sets a real walkthrough window on the call with a contractor based close to Lapel.
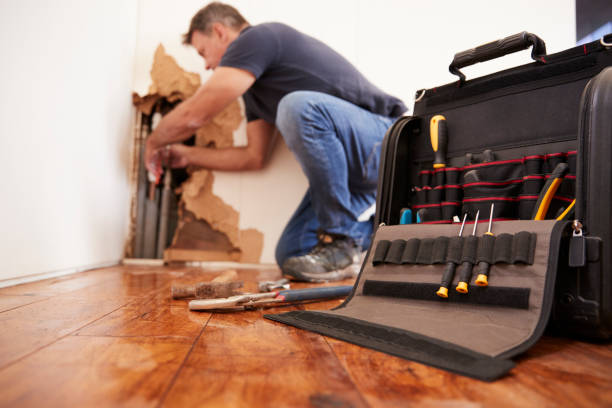
Rebuild crews carry texture hoppers, knockdown knives, trim saws and coping saws, not air movers. That gear and some patience are what make a patched wall look like it was never cut.
Each job follows the scope of loss: a written list of every material that came out during mitigation and has to go back in.
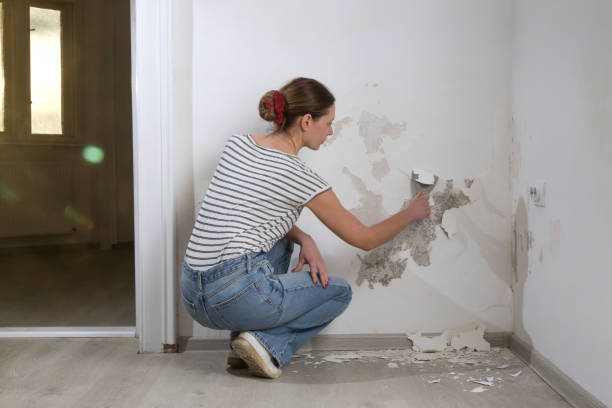
Flood cuts get closed with new board, then tape, three coats of mud and sanding. The hard part is texture: orange peel, knockdown and skip trowel all have to blend into the wall that stayed.
MDF base that drank up water stays swollen, so it gets pulled and replaced with the same profile. After a kitchen leak, toe-kicks and sometimes the whole sink base cabinet need replacing too.
Laminate and LVP tend to get replaced since water sits below the click joints and the core swells. Solid hardwood caught early can often be sanded and refinished; engineered planks rarely come back.
A chip is cut from an undamaged wall and taken to the paint counter for a computer match. Repainting full walls to the corners avoids the shiny halo you get from spot painting.
Furniture, boxes and electronics can be photographed, inventoried, packed out and stored while the rebuild runs. The itemized list doubles as proof for the contents portion of the claim.
Before and after photos, the scope, the mitigation drying records and the final invoice go into one file. Adjusters move faster when the paperwork answers their questions before they ask them.
The first half of any water loss is mitigation: stop the source, pull the water, remove what will not dry and run dehumidifiers until the meter says done. What comes after is restoration, and the work looks a lot more like a remodel than an emergency call.
Take a dishwasher supply line that dripped under the cabinets for days before anyone noticed. Mitigation pulls the toe-kicks, opens the cabinet bases for airflow and dries the subfloor. Restoration is the part where someone finds a matching toe-kick, replaces the swollen sink base and ties new flooring into the old at the doorway.
Or think about an upstairs toilet that overflowed and rained down through the kitchen ceiling. Once the soaked ceiling board is down and the joists read dry, someone still has to hang new board overhead, match the texture and repaint the whole ceiling.
The crews that are great at fast tear-out are not always the ones you want doing finish work in your living room.
Plenty of companies only do the dry-out. Ask any contractor directly whether the rebuild is included, and make sure the answer is in the written scope.
The process has four steps, and the first is a short phone call.
Tell the dispatcher what was removed during mitigation and whether you have an open claim. We route you to an independent local rebuild contractor and lock in a walkthrough time on the same call.
Your contractor checks every affected room with a meter first, because closing up a wet wall is the most expensive mistake in this trade.
You get a written scope with every line item: drywall, trim, flooring, paint, cabinet work and contents handling. Many contractors submit it to the adjuster and add a supplement if more damage shows up behind a wall.
When the last coat of paint is dry, you walk the house with the contractor and build a punch list. Sign off only after the punch list is cleared, and ask for any workmanship warranty in writing.
The dishwasher line had been leaking for who knows how long. The dry-out company left us with no toe-kicks and a sink base that looked like a sponge. The referral line put me in touch with a local contractor who matched the cabinet toe-kicks and talked to our adjuster so I was not stuck in the middle.
Upstairs toilet overflowed and a big chunk of the kitchen ceiling had to be cut out a week before the holidays. The contractor I was connected with hung new board, matched the knockdown and painted the whole ceiling. I honestly cannot find the patch.
I figured the hallway oak was headed for the dumpster. The contractor took readings, confirmed it was solid hardwood that had dried out, and sanded and refinished it instead of tearing it out. Honestly the floor looks better now than before the leak.
My rental had three rooms stripped to the studs and a tenant asking every day when it would be done. The contractor gave me a line-item scope the insurance company accepted almost as written, and the paint matched on the first try.
One call connects you with an independent local contractor who handles the rebuild after water damage.
Mitigation is the emergency work that keeps damage from growing: water removal, tear-out, antimicrobial and drying. Restoration puts the house back: drywall, texture, trim, flooring, cabinets and paint.
Insurance usually treats them as two parts of the same claim, often with two separate estimates.
It depends on the scope. A single room of drywall and paint can be done in days, while a kitchen with cabinets and new flooring can run several weeks. The delays usually come from backordered materials and claim approvals rather than the actual work.
Get a written schedule from the contractor that shows which trade comes when.
Generally you can. Your carrier may recommend a preferred vendor, but most policies let you hire the contractor you pick. Read your policy and confirm with your adjuster before signing anything.
A lot of the independent contractors we refer deal with adjusters every week and write estimates the way carriers like them.
Often, if they are solid hardwood and were dried quickly. Mild cupping can settle once the moisture content comes back to normal. A good contractor takes readings over a few days before deciding whether to sand and refinish.
Boards that have crowned, split or lifted, and most engineered planks, usually have to be replaced.
A careful contractor tests the texture on scrap and paints whole walls to the corners so the repair blends in. Paint is matched from a chip of the existing wall, not from a guess at the color name.
Look at the texture sample before it goes up, and check the finished wall in daylight before you sign off.
The contractors we refer live and work in the area, so they know the local housing stock and the local permit office.
Older houses close to downtown Lapel often have plaster and real wood trim, which take more work to match. Newer neighborhoods have MDF trim and LVP, which are easy to buy but swell fast once wet.
Describe the open walls and we will route your call to a local pro.
Call +1-877-637-9008